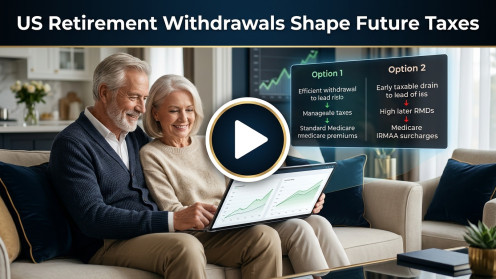
When it comes to retirement planning, the way you choose to withdraw funds can have a lasting impact on your taxes and even your healthcare costs down the road. For example, two retirees with identical $2.1M portfolios might end up with very different tax bills simply because of how they structured their withdrawals early on—leading to changes in Required Minimum Distributions (RMDs) and possible Medicare surcharges later.
A portfolio split between taxable savings and a traditional IRA generated $117,400 per year, but where each asset sits can influence both your current tax efficiency and the pressure you’ll feel from taxes in the future. For 2026 joint filers, keeping your Modified Adjusted Gross Income (MAGI) at or below $218,000 means you’ll stay at standard Medicare premiums, but going just one dollar over could bump your Part B premium by nearly $284, plus add Part D surcharges.
Some people consider draining taxable accounts first, but that can leave IRA balances to grow, resulting in larger RMDs later. On the other hand, planning IRA withdrawals or conversions before you hit RMD age might lower your future tax burden—and help keep you under those IRMAA cliffs. Before year end, it’s smart to model different RMD paths, monitor conversions, and review your IRA holdings for risks like floating-rate investments, leverage, or concentration. This kind of proactive approach is what I aim to bring to every financial conversation—helping you understand your options so you can feel secure and prepared for the future.
Leave a Reply